Sheikh Sameer
Financial Literacy Among Students
“My father in my childhood days used to tell me that earning money or generating money is easy, but spending money needs real and proper understanding of where and how to spend.” That line stayed with me because it captures a truth many people learn only after making costly mistakes. I later bought Rich Dad Poor Dad to understand that idea more clearly, and that was when I came across the term financial literacy. For students, this concept is not just about money; it is about choices, discipline, responsibility, and the ability to build a stable future.
Financial literacy among students is becoming more important than ever in a world where money decisions start earlier and mistakes can follow faster. Many students receive pocket money, part-time income, online earnings, or scholarships, yet few are taught how to manage them well. They may know how to spend, but not how to budget, save, compare value, or avoid debt traps. In this sense, financial literacy is not a luxury subject; it is a life skill.
Financial literacy means understanding how money works in daily life. It includes earning, saving, budgeting, investing, borrowing, and planning for the future. For students, it also includes learning the difference between wants and needs, understanding the value of delayed gratification, and making informed decisions instead of impulsive ones. A financially literate student is not necessarily rich, but that student is more likely to be responsible and prepared.
In many homes, children are taught to study hard so they can get a good job, but they are not taught what to do with the money they earn later. This gap creates problems. A person may have a degree and a salary, yet still live paycheck to paycheck because money habits were never developed. That is why financial literacy should begin early, ideally during school and college years, when habits are still forming.
Why students need it
Students live in a time of easy spending. Mobile apps, online shopping, instant food delivery, subscriptions, and digital payments make money feel less real than cash once did. When spending is just a tap away, it becomes easier to lose track of where money goes. Students often underestimate small expenses, but those small expenses add up quickly.
Financial literacy helps students avoid this trap. It teaches them to track spending, set priorities, and build habits that support long-term stability. A student who understands money is better equipped to handle emergencies, avoid unnecessary debt, and make thoughtful decisions about education and lifestyle. These lessons are especially valuable because student years are often the first time a person begins managing money independently.
Lessons from childhood
The wisdom shared by parents often becomes the first lesson in money management. The father’s advice in the opening line is powerful because it reminds us that making money is only one part of life. Spending money wisely is a separate skill, and in many cases, it is harder than earning it. A person can work hard to bring money in, but without discipline, that money can disappear too quickly.
This is why books like Rich Dad Poor Dad resonate with so many readers. They challenge the idea that income alone creates wealth. Instead, they show that financial behavior matters just as much as income. For students, this lesson is especially relevant because they are often at the stage where beliefs about money are being shaped. If they learn early that money should be managed, not merely spent, they gain a lifelong advantage.
Core parts of financial literacy
Financial literacy is not one single skill. It is made up of several connected ideas.
Budgeting: Knowing how much money comes in and how much goes out.
Saving: Setting aside money for future use or emergencies.
Spending wisely: Choosing value over impulse.
Debt awareness: Understanding loans, interest, and repayment.
Investing basics: Learning how money can grow over time.
Planning: Setting short-term and long-term financial goals.
Each of these matters for students. Budgeting teaches control. Saving teaches patience. Spending wisely teaches discipline. Debt awareness protects against bad financial decisions. Investing introduces the idea that money can work for you, not only the other way around. Planning brings all these habits together into a clear direction.
Budgeting as a student skill
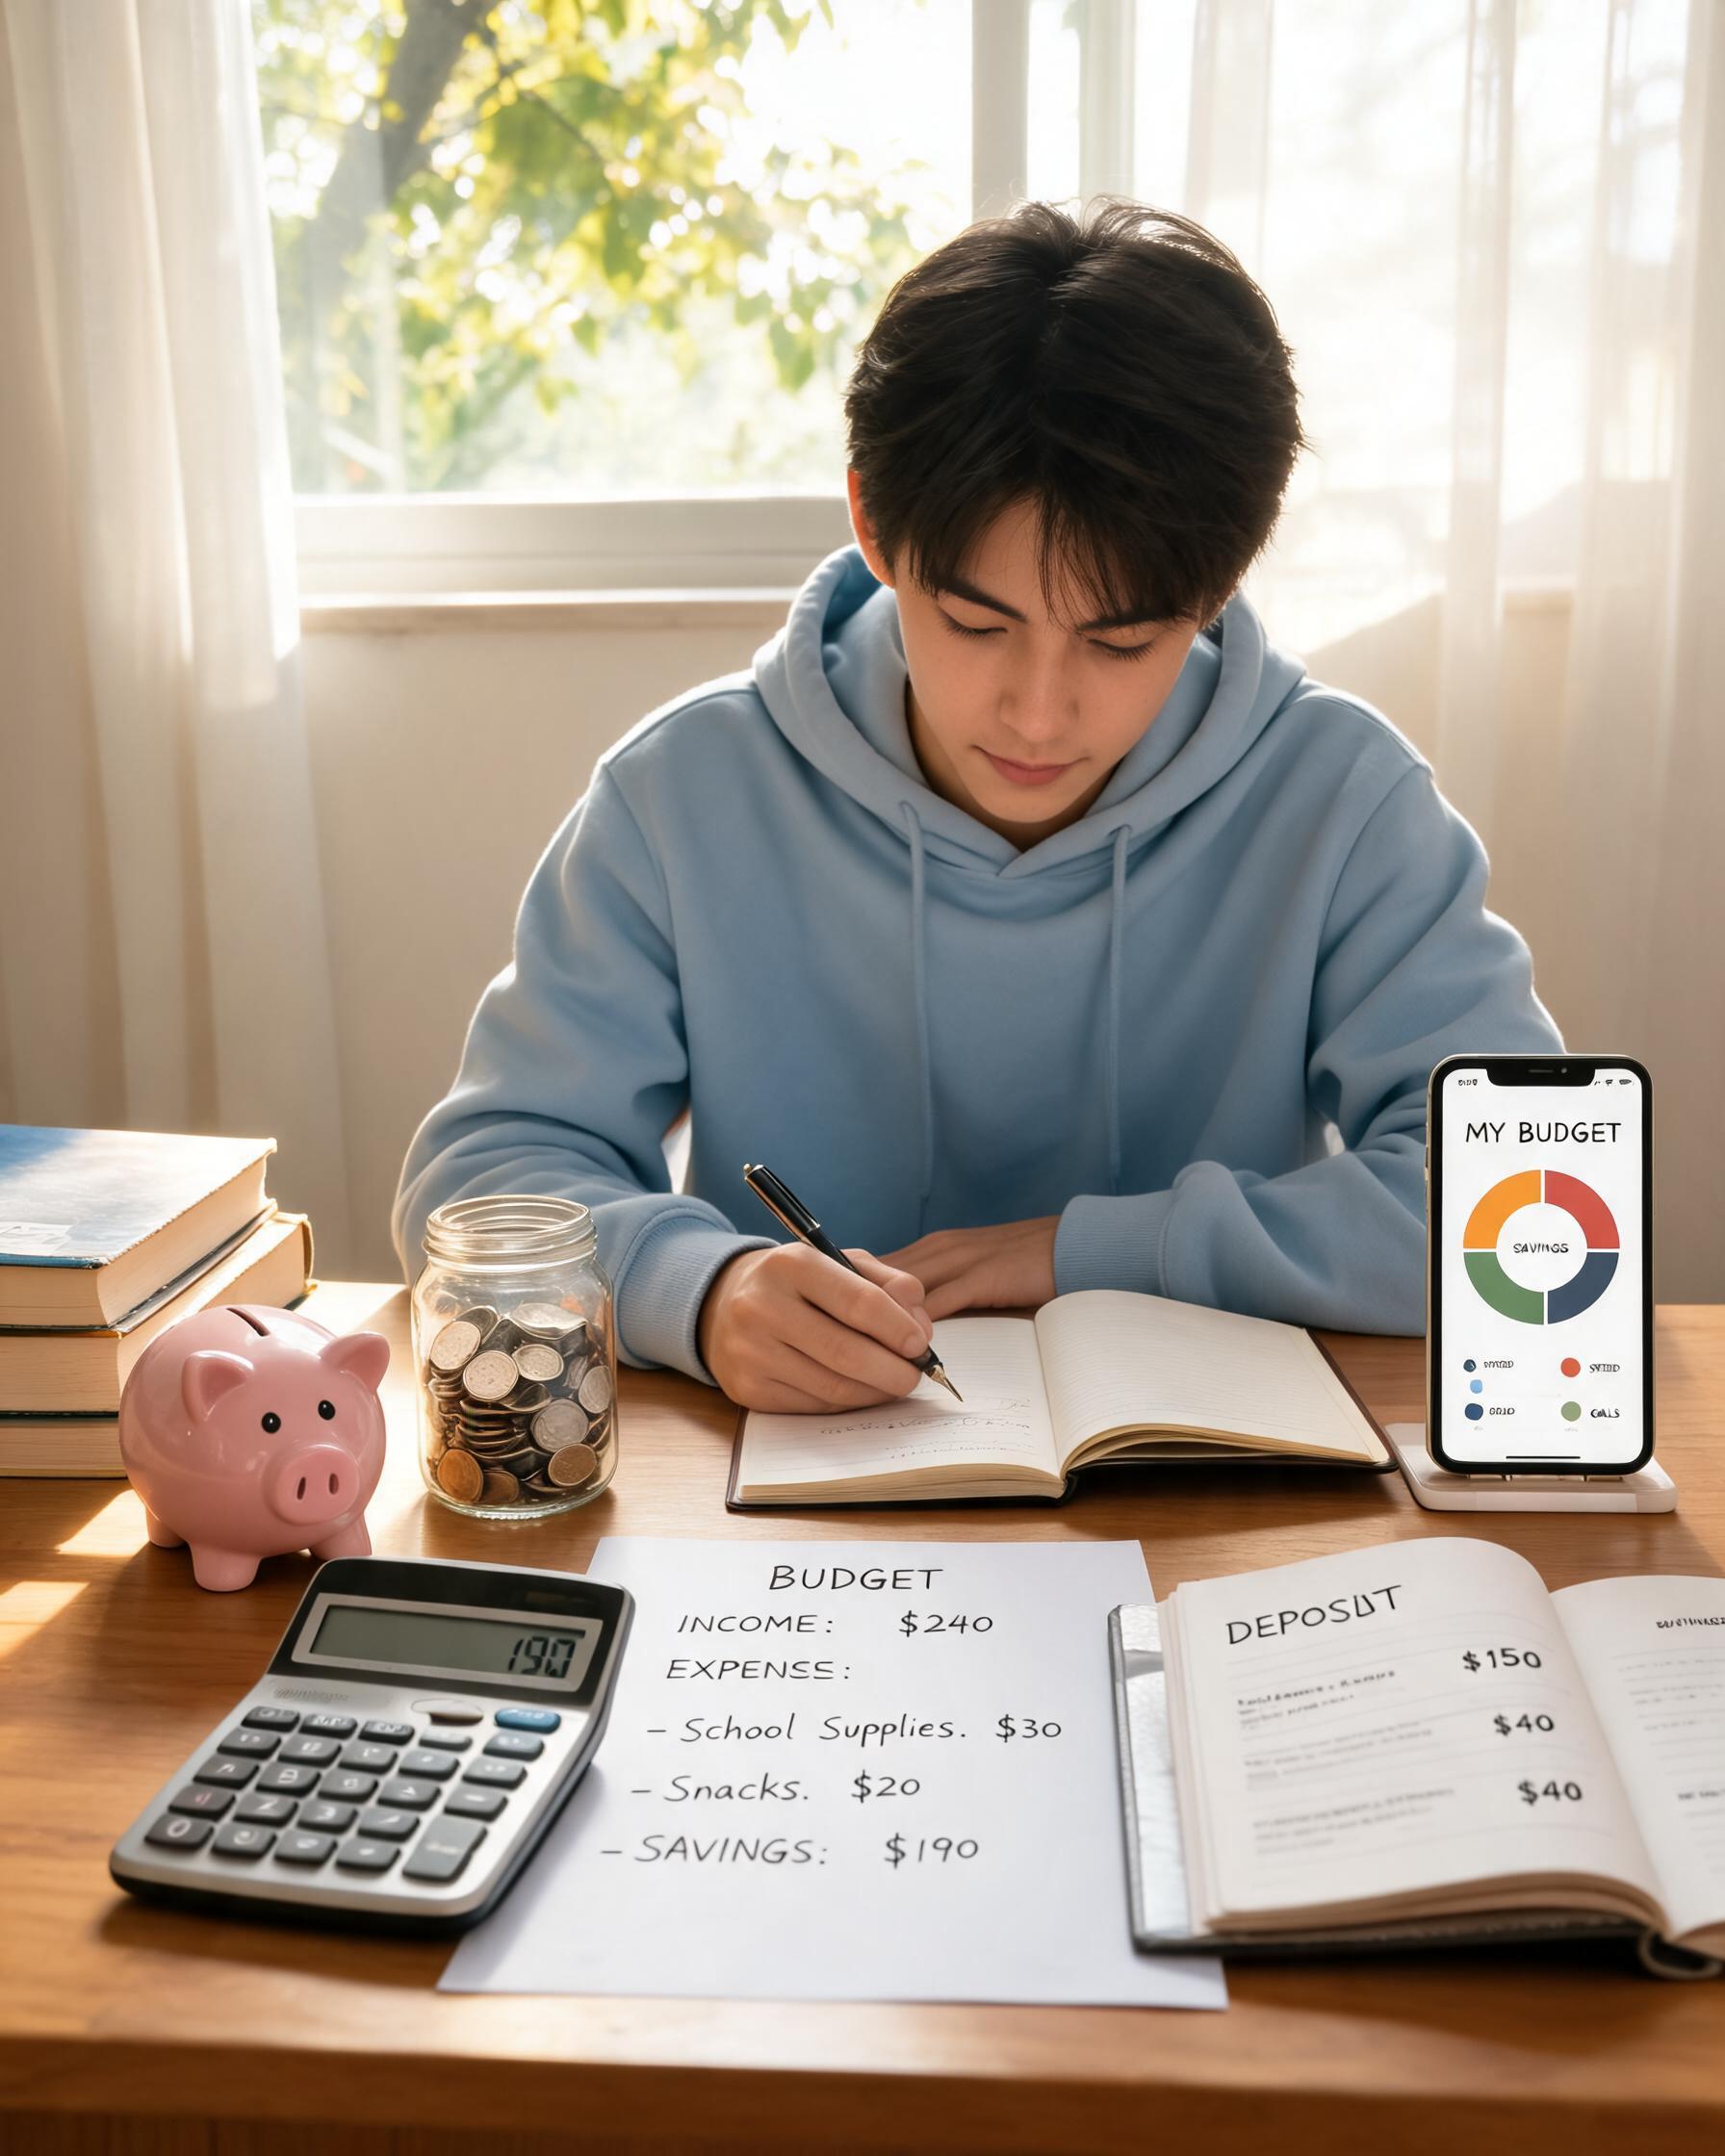
Budgeting is often the first real money skill a student should learn. Even if a student receives only a small amount each month, a budget helps that money last longer and do more. A simple budget might divide money into categories such as food, transport, academic needs, savings, and personal spending. The goal is not to restrict life but to create awareness.
Many students think budgeting is only for adults with salaries, but that is a misunderstanding. In fact, students may benefit more from budgeting because their income is usually limited. When money is limited, every decision matters more. Budgeting also teaches self-control, which is useful far beyond finance. A student who can manage a budget is learning how to manage priorities.
Saving and discipline
Saving is one of the most important habits in financial literacy. Students often want instant rewards, but saving teaches delayed satisfaction. Instead of spending everything now, a financially aware student sets aside some money for later. That later could mean an emergency, a book, a course, travel, or even an investment opportunity.
Saving does not require a large income. Even small amounts saved regularly can build a meaningful reserve. More importantly, saving creates confidence. A student who has some savings feels less panic when unexpected expenses appear. This habit builds independence and reduces pressure on parents or others. Over time, saving becomes more than a money habit; it becomes a mindset.
Spending and self-control
Spending is where many financial mistakes begin. Students are often surrounded by pressure to buy the latest phone, wear fashionable clothes, eat out frequently, or follow trends on social media. These choices may seem harmless, but repeated impulsive spending can weaken financial stability. Financial literacy helps students pause before they spend.
A useful principle is to ask whether a purchase is a need, a want, or a temporary emotion. Many purchases are driven by boredom, peer pressure, or the desire to impress others. Real financial maturity means learning to separate emotional desire from practical necessity. This does not mean a student should never enjoy money. It means enjoyment should be intentional, not automatic.
Debt and credit
Another major part of financial literacy is understanding debt. Many students enter adulthood without knowing how loans, credit cards, and interest actually work. This is dangerous because debt can become expensive very quickly if it is not understood properly. A student who borrows without planning may end up paying much more than expected.
Credit is useful when managed responsibly, but it can also create stress when used carelessly. Financial literacy teaches that borrowed money should have a purpose and a repayment plan. Students should understand that a loan is not free money. It is a commitment that affects future choices. Learning this early can prevent years of financial trouble later.
Investing and growth
Many students hear about investing but think it is only for wealthy people. That belief is false. Financial literacy introduces students to the basic idea that money can grow over time through informed decisions. Even if students are not ready to invest large amounts, they should understand concepts like risk, return, and compounding.
The earlier a person learns about investing, the better prepared they are for adulthood. Students do not need to become experts immediately, but they should become comfortable with the language of finance. This knowledge reduces fear and confusion later. It also helps students see that saving alone is not always enough; sometimes money needs to be placed where it can grow.
Role of schools
Schools have a major role to play in financial literacy. Many education systems still focus heavily on examinations and academic performance while giving little attention to practical life skills. Students may leave school knowing formulas and dates, but not how to make a budget or understand interest. That gap should be addressed.
Schools can include financial literacy through simple lessons, workshops, simulations, and real-life examples. Students can be taught how to open a bank account, read a payslip, understand online payments, and compare prices. These lessons do not require complex theory. They require relevance. When students see finance connected to daily life, the subject becomes useful instead of abstract.
Role of parents
Parents are often the first financial teachers. Children observe how adults spend, save, argue, plan, and prioritize. Even when parents do not formally teach money management, their habits still shape their children’s attitudes. This is why family conversations about money matter.
Parents can help by giving children small responsibilities, such as managing pocket money or saving for a desired item. These experiences teach consequences in a safe way. Children who learn money habits at home are more likely to carry them into adulthood. The earlier this starts, the stronger the foundation becomes.
Digital age challenges
The digital age has made financial literacy both more important and more difficult. On one hand, students now have access to online courses, finance videos, apps, and educational content. On the other hand, they also face nonstop advertising, influencer culture, and frictionless buying. This combination can encourage careless spending.
Students need to understand that digital convenience does not always mean financial wisdom. One-click purchases, easy subscriptions, and buy-now-pay-later options can hide the real cost of consumption. Financial literacy helps students remain alert in this environment. It teaches them to slow down, review choices, and avoid being manipulated by marketing.
Building habits early
Good financial habits are easier to build early than late. A student who learns to save a little, spend carefully, and think ahead is already preparing for adulthood. These habits may seem small, but they create discipline over time. Just as reading builds knowledge through repetition, money habits build financial strength through consistency.
Students should think of financial literacy as part of personal growth. It is linked to confidence, independence, and decision-making. A student who understands money does not become greedy or obsessed with wealth. Instead, that student becomes more capable of using money as a tool rather than being controlled by it.
A practical example
Consider two students who receive the same monthly allowance. One spends most of it quickly on snacks, entertainment, and impulse purchases, leaving nothing for unexpected needs. The other tracks expenses, saves a portion, and buys only what is necessary. After a few months, the second student has less stress and more flexibility. This simple difference can shape future behavior in powerful ways.
The example shows that financial literacy is not about how much money a student has. It is about how that money is managed. Small habits repeated over time can produce very different outcomes. That is why financial education should not wait until a person starts earning a full salary.
Financial literacy among students is one of the most important life skills of our time. It teaches that money is not only about earning but also about managing wisely. My father’s advice in childhood and the lessons drawn from Rich Dad Poor Dad point to the same truth: understanding money is essential if we want to use it well. Students who learn this early gain more than financial skill; they gain confidence, discipline, and freedom.
In a world full of spending temptations and financial confusion, students need guidance more than ever. Schools, parents, and communities should work together to make financial literacy a normal part of education. If students learn to budget, save, spend wisely, and think ahead, they will enter adulthood with stronger foundations. And that may be one of the most valuable lessons education can ever provide.